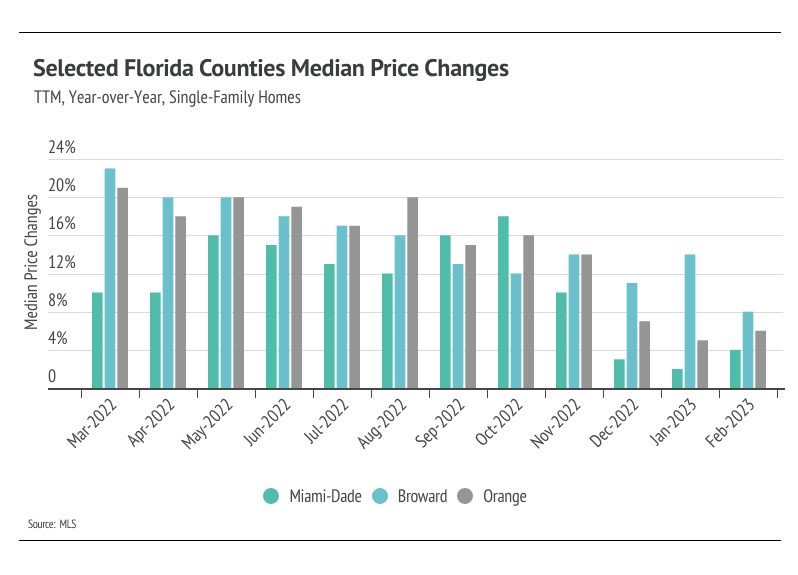
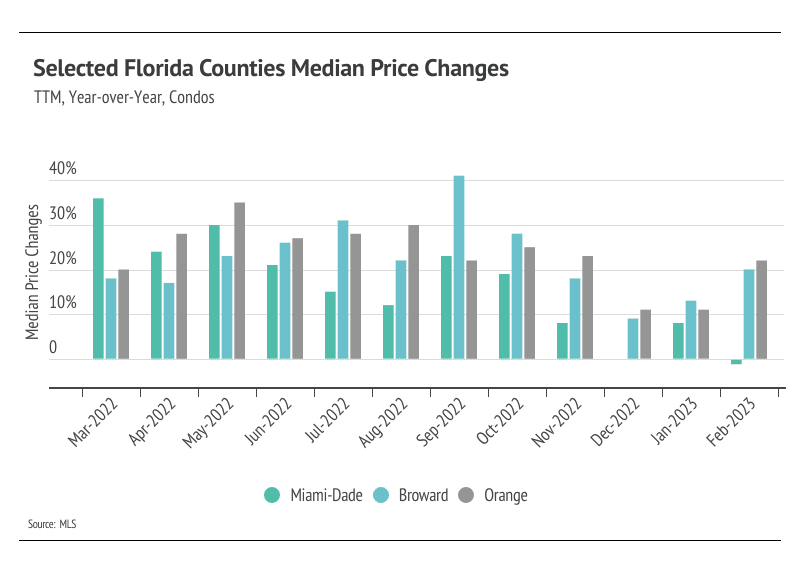
March Market Report

March 16, 2023

March Market Report
The Big Story
 
Mixed Signals
 
Quick Take:
  • Home sales fell for the 12th month in a row, while, according to the National Association of Realtors, the median sale price continued its seven-month decline from its June 2022 peak. However, data from realtor.com indicate the median price per square foot rose slightly in January and February 2023.
  • U.S. employment is booming, which largely alleviates our concerns that a full economic recession will occur anytime soon. Yet, consumer confidence is low, and increasing consumer credit card debt and delinquency are early signs of economic instability.
  • Inflation and mortgage rates are still high, which has massively slowed the housing market, as buyers and sellers are still adjusting to the new market conditions.
Note: You can find the charts & graphs for the Big Story at the end of the following section.
 
Ins and outs of a housing market slowdown
 
Banking analysts and economists are starting to cry recession again, as the Fed is faced with a longer road than anticipated to lower inflation. Over the past year, the Fed has raised its benchmark rate by 4.5% and shrunk its balance sheet by over $600 billion. At a minimum, we expect the Fed to raise its target interest rates to 5.25% by the end of the year, which will only happen if they continue to raise rates by 0.25% over the next three quarters. There is a very real chance that rates will move higher than 5.25% because the Fed has such limited tools to combat inflation. The economy is still in the early days of disinflation — a temporary slowing of the pace of price inflation — and the Fed has indicated that they’ll keep rates high until inflation is under control. This uncertainty around interest rates has hit the housing market especially hard.
 
Mortgage rates have been volatile, making it more challenging for buyers in terms of financing and affordability. Historically, the spread between the 10-year U.S. Treasury Securities and 30-year mortgage rates has been around 1.8%. Currently, 10-year treasuries are yielding 4.08%, while the average 30-year mortgage rate is 6.65%, a spread of 2.57%. Buyers and sellers are still getting used to the dramatic mortgage rate hikes that started in early 2021. Even looking back one year, the price difference is substantial. When we account for the 5% year-over-year increase in median price per square foot of a home in the United States, plus interest rates rising over 2.5%, the monthly cost to finance a home rose by 41%. Looking back two years, the monthly cost has risen by 81%.
 
The housing market has done what you’d expect of any market when cost rises so rapidly: It slowed down substantially. The number of home sales in 2022 was exceptionally low, and we expect sales to remain low in 2023, since mortgage rates will likely stay between 6 and 7% on average for the rest of the year. Additionally, the number of active listings remains historically low but isn’t as large of a concern as it was in 2020 and 2021 due to the large drop in demand.
 
We do want to be clear that the housing market isn’t in a recession, nor is the rest of the country. Still, potential homebuyers, and consumers overall, have far less buying power than they did in the very recent past. The broad economy is still expanding, the unemployment rate is at a 53-year low, and wage growth has been substantial, making a full recession unlikely in the near future. Homebuyers can expect a less competitive market but must continue to be decisive, as desirable homes are still selling quickly.
 
Different regions and individual houses vary from the broad national trends, so we’ve included a Local Lowdown below to provide you with in-depth coverage of your area. In general, higher-priced regions have been hit harder by mortgage rate hikes than less expensive markets due to the absolute dollar cost of the rate hikes. As always, we will continue to monitor the housing and economic markets to best guide you in buying or selling your home.
 
Big Story Data
 
Chart of active listings and median listing price per square foot from August 2016 to February 2023.
Chart of weekly 15- and 30-year U.S. mortgage rates, December 2021 to March 2023.
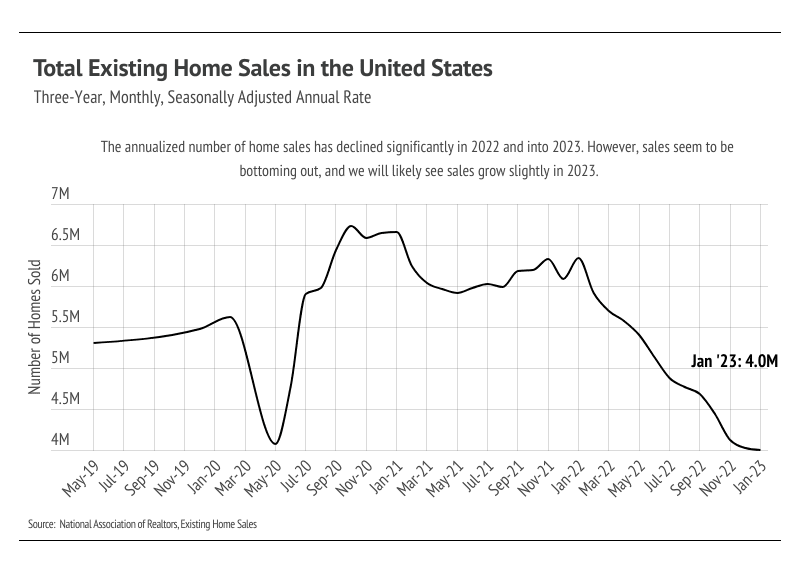
Line chart of U.S. existing home sales, declining to 4.0 million in January 2023.
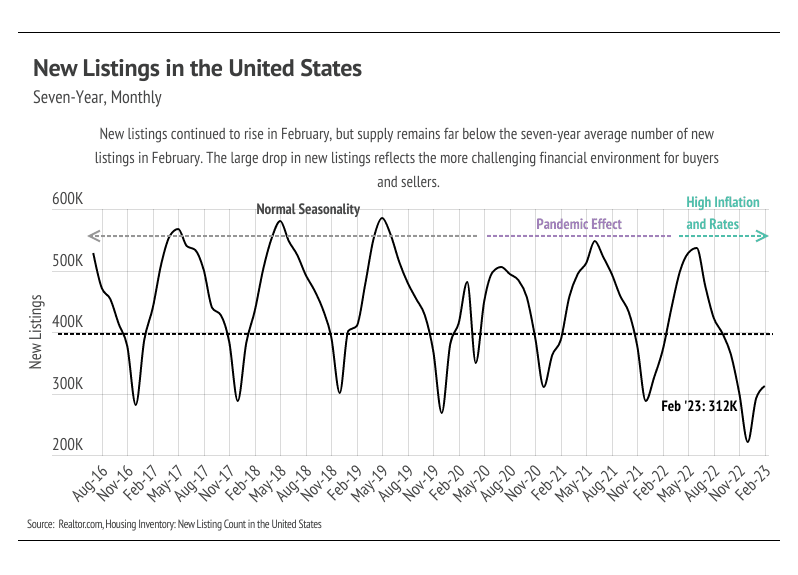
Line chart of U.S. new listings, August 2016–February 2023, showing a February 2023 count of 312,000.
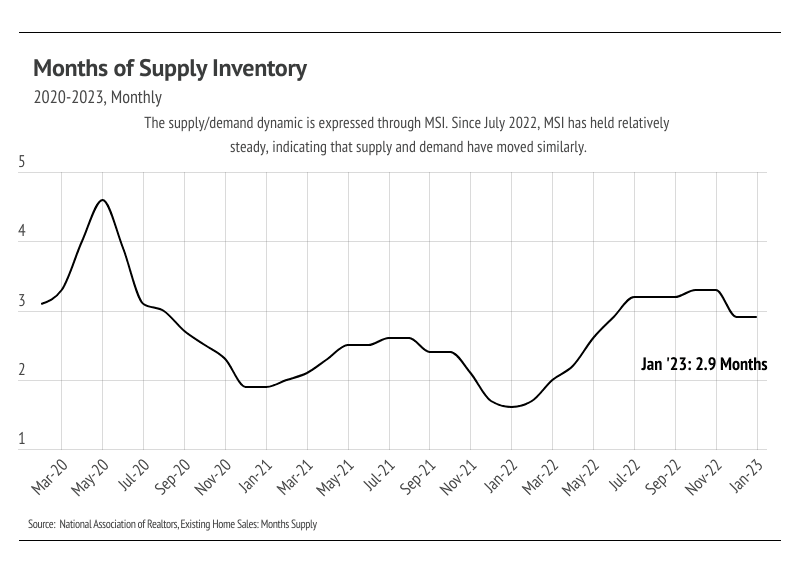
Line chart of months of supply inventory from 2020 to January 2023, ending at 2.9 months.
The Local Lowdown — Miami-Dade, Broward, and Orange Counties
 
Quick Take:
  • Active listings in the selected Florida markets dropped further in February, with the exception of Broward County condos, as fewer listings came to market. Inventory across the selected markets is still historically low.
  • Home prices rose month over month with the exception of Miami condo prices, which fell slightly, signaling that low inventory and seasonality are still affecting pricing despite higher mortgage rates.
  • Months of Supply Inventory declined as sales increased and homes sold faster, indicating the market has become more competitive, although the Miami-Dade market still favors buyers.
Note: You can find the charts/graphs for the Local Lowdown at the end of this section.
 
Typical and atypical seasonal trends
 
This time of year, we usually see both inventory and sales increasing steadily through mid-summer. Inventory is able to grow, even with increasing sales, due to the relatively high number of new listings that come to market in the first half of the year. However, the number of new listings actually decreased from January to February in all markets except for single-family homes in Orange County, which is an early sign that inventory will struggle to grow this year. Although we expect sales to be more muted this year, demand could start significantly outpacing supply, especially if sales continue to rise without being met by more new listings. Even with higher mortgage rates, the selected Florida markets are experiencing greater demand than much of the country for a couple of key reasons. People simply want to live in Florida, and homes are still somewhat affordable, which translates to more market participants.
 
Florida real estate has proven to be one of the most stable and resilient markets in the country. Single-family home prices have increased across the selected markets year over year, and looking back two years, prices have increased massively across counties. Miami-Dade condo prices fell year over year but have maintained much of the large gains in 2020 and 2021. Homebuyers in Florida can actually find a home within budget, which allows for a conventional loan to finance the purchase, and they can expect to refinance at some point in the future, which will decrease their monthly costs. The next three months will give us a clearer picture of how buyers and sellers are reacting to the current market conditions, but early signs point to more competition as we enter the spring season.
 
Inventory still historically low
 
Although single-family home inventory across markets is higher than last year, active listings fell precipitously in 2020 to what has become the new normal over the past two years. Inventory declined in February 2023 across markets and dwelling types with the exception of Broward County condos, which rose slightly. Higher interest rates have dropped incentives for potential sellers to enter the market, since sellers usually also must buy a new home. Homeowners either bought or refinanced recently, locking in a historically low rate, which means they aren’t selling and fewer listings are coming to market. Many potential buyers were priced out of the market as interest rates rose; however, interest rates have been higher for enough time that buyers are more comfortable re-entering desirable markets like Florida. Currently, buyers aren’t facing anything similar to the hypercompetitive 2020 and 2021 markets, but we will likely start to see more competition in the spring. New listings and sales both fell substantially year over year. We still expect some inventory growth in the first half of 2023, but inventory will likely remain low.
 
Months of Supply Inventory dropped, indicating a market shift
 
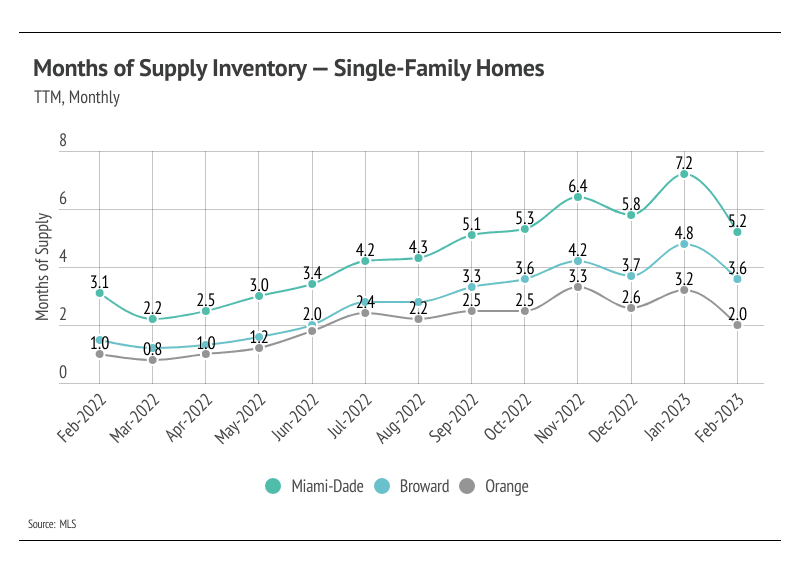
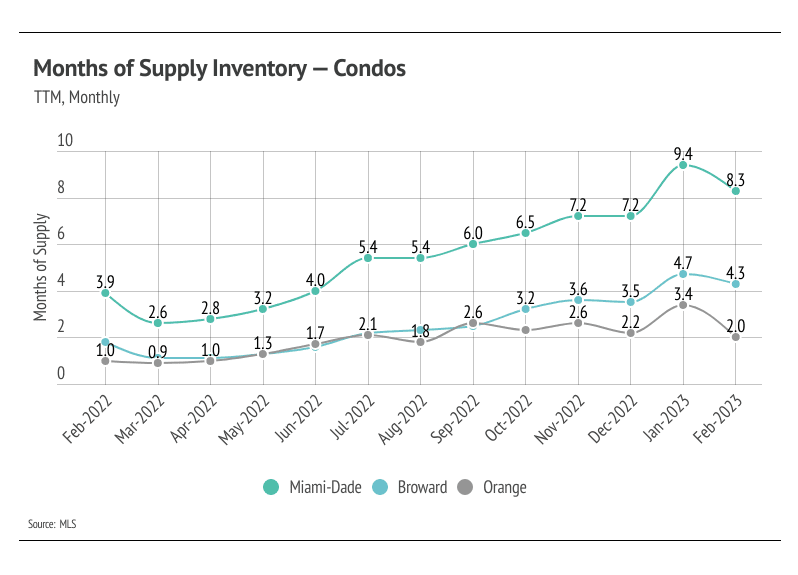
Months of Supply Inventory (MSI) quantifies the supply/demand relationship by measuring how many months it would take for all current homes listed on the market to sell at the current rate of sales. The long-term average MSI is around four to five months in Florida, which indicates a balanced market. An MSI lower than four indicates that there are more buyers than sellers on the market (meaning it’s a sellers’ market), while an MSI higher than five indicates there are more sellers than buyers (meaning it’s a buyers’ market). MSI dropped in February, indicating that the markets are shifting toward more competitive for buyers. Currently, Miami-Dade favors buyers, Orange County favors sellers, and Broward County is more balanced. The sharp drop in MSI occurred due to homes selling more quickly and fewer new listings coming to market.
 
Local Lowdown Data
 
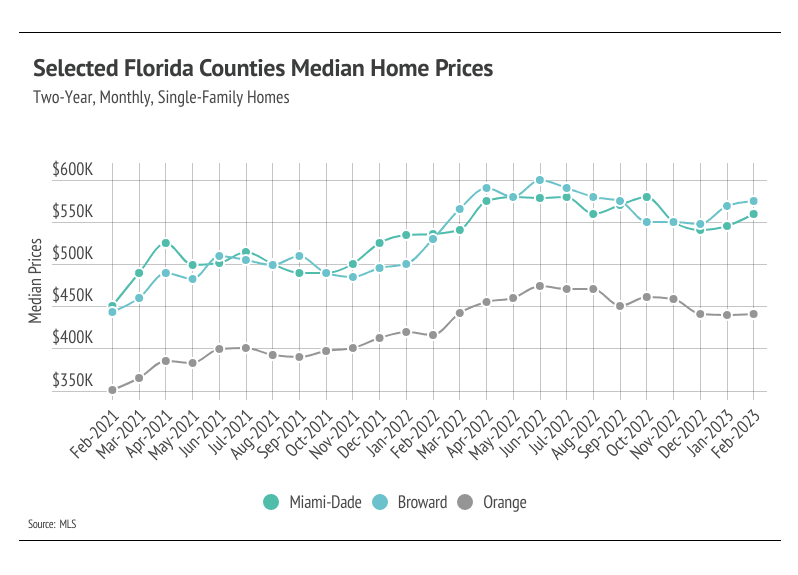
Chart comparing monthly median single-family home prices in Miami-Dade, Broward, and Orange counties, 2021–2023.
Chart comparing year-over-year single-family home median price changes in Miami-Dade, Broward, and Orange counties.
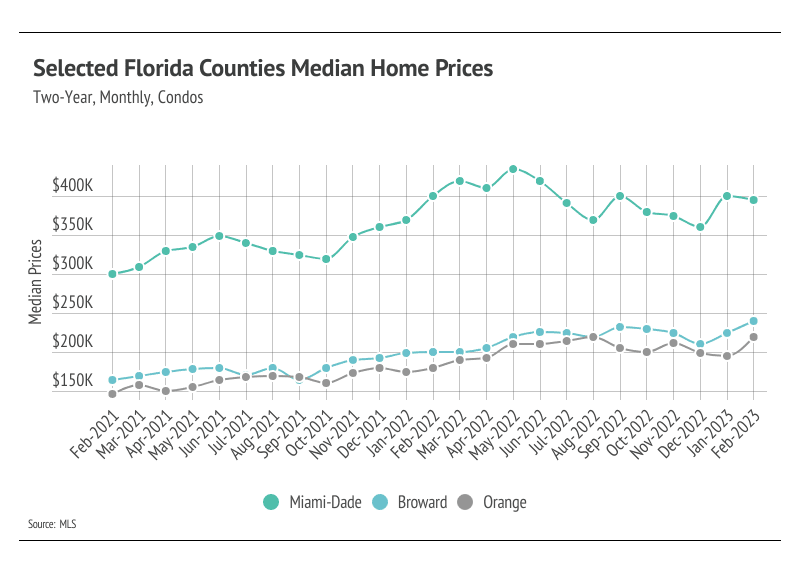
Line chart comparing monthly median condo prices in Miami-Dade, Broward, and Orange counties, February 2021–February 2023.
Chart of year-over-year condo price changes in Miami-Dade, Broward, and Orange counties, March 2022–February 2023.
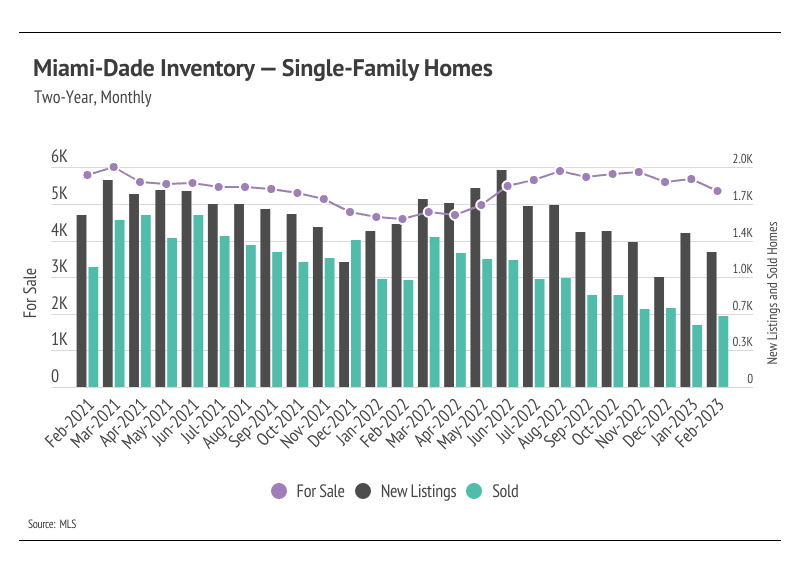
Miami-Dade single-family home inventory chart showing monthly listings, homes for sale, and sales from February 2021 to February 2023.
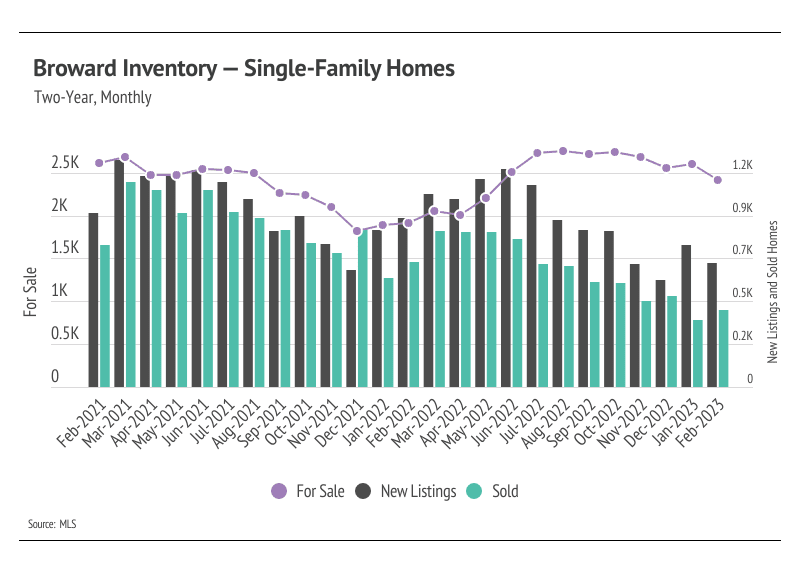
Chart of Broward single-family home inventory, new listings, and sales from February 2021 to February 2023.
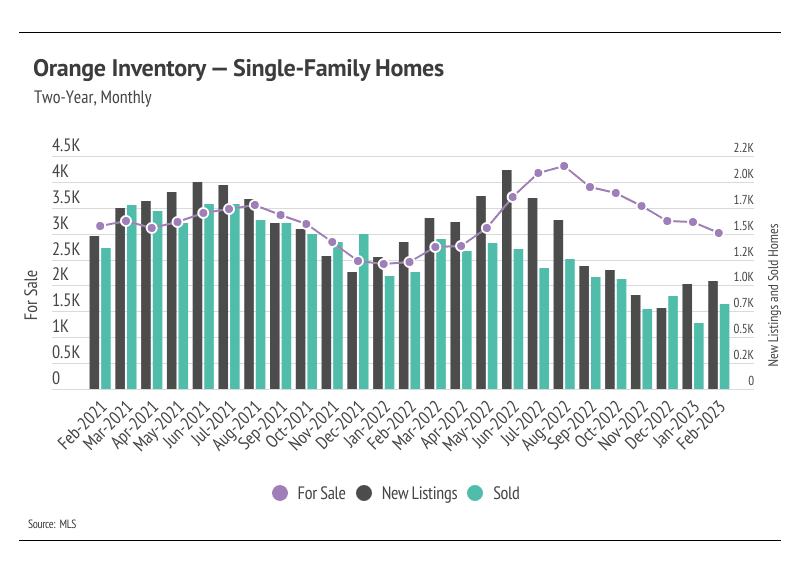
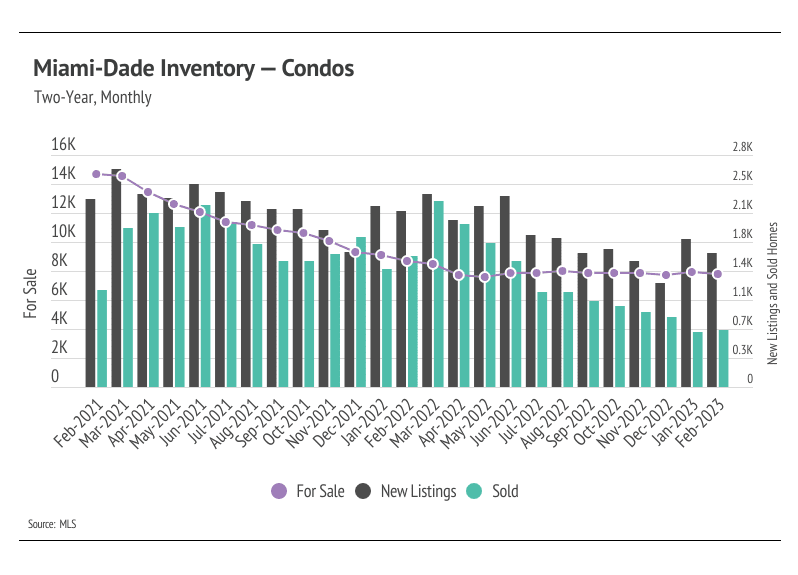
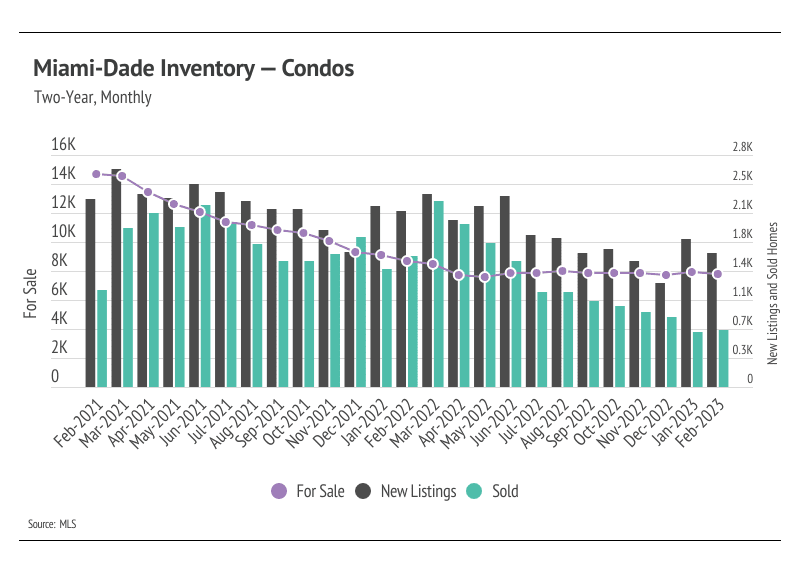
Orange single-family home inventory chart comparing homes for sale, new listings, and sold from February 2021 to February 2023.Chart of Miami-Dade condo inventory, new listings, and sales from February 2021 to February 2023.Miami-Dade condo inventory chart, showing monthly for-sale listings, new listings, and sales from February 2021 to February 2023.
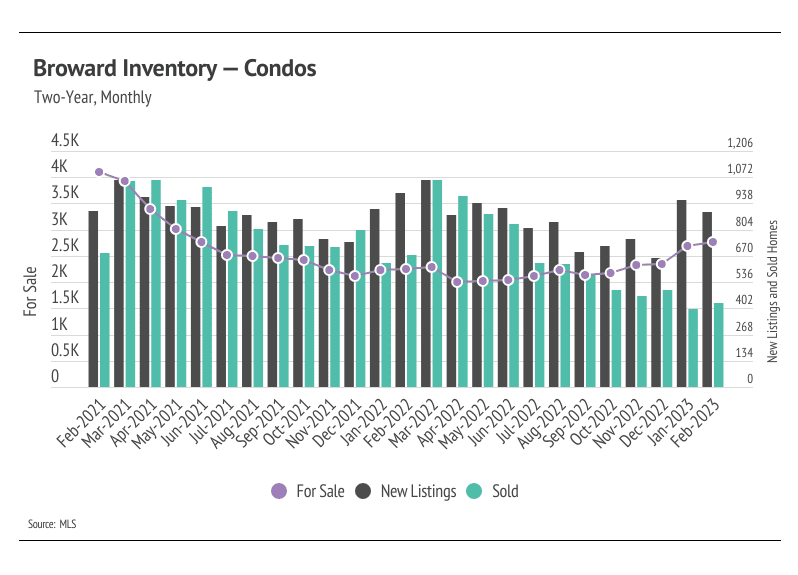
Chart of Broward condo inventory, new listings, and sales from February 2021 to February 2023.
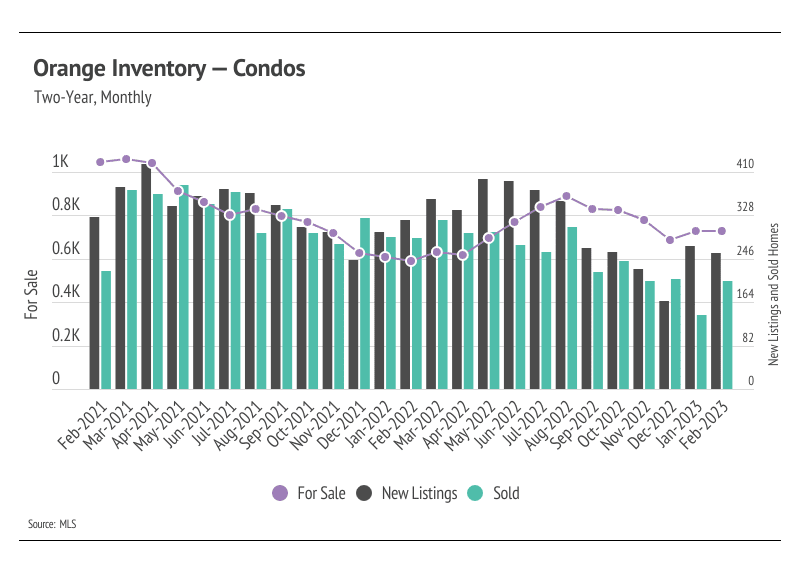
Monthly Orange condo inventory chart comparing homes for sale, new listings, and sales, February 2021–February 2023.
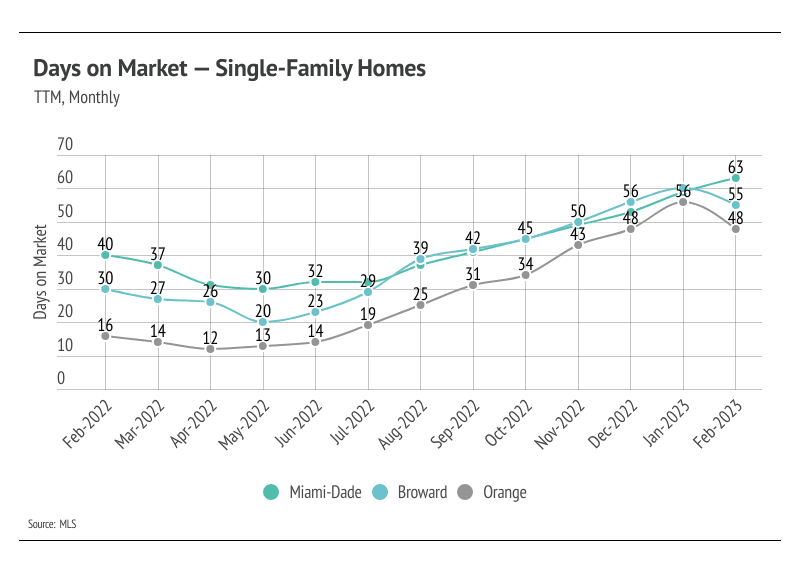
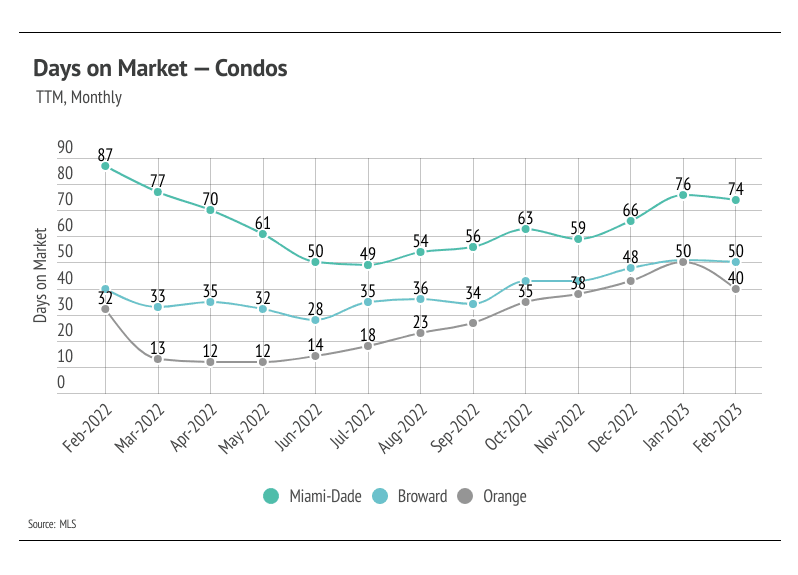
Line chart comparing monthly days on market for Miami-Dade, Broward, and Orange, February 2022–February 2023.
Monthly condo days-on-market chart comparing Miami-Dade, Broward, and Orange from February 2022 to February 2023.
Months of supply chart for Miami-Dade, Broward, and Orange, February 2022–February 2023.
Line chart comparing monthly condo supply in Miami-Dade, Broward, and Orange from February 2022 to February 2023.
 

Recent Blog Posts

Stay up to date on the latest real estate trends.
Market Report

Why Developers Are Betting Millions on Smaller Luxury Buildings in Coconut Grove

Lucas Boccheciampe  |  October 29, 2026

A new Coconut Grove development has secured $58 million in construction financing for just 48 luxury residences. Would wealthy buyers rather live in a 70 story skyscra… Read more
Who Is Buying Miami’s $10 Million Homes?

Lucas Boccheciampe  |  October 22, 2026

Miami Dade recorded 194 home sales of $10 million or more through August 2026, already surpassing the total for all of 2025. Who has enough money to keep this market m… Read more
The Return of the Cash Buyer: Why Miami’s Wealthy Have an Advantage in 2026

Lucas Boccheciampe  |  October 15, 2026

Mortgage rates are around 7%, but many wealthy Miami buyers do not need a mortgage at all. How much of an advantage does cash really provide?
Curved high-rise balcony with glass railings and seating overlooking a waterfront skyline at sunset.
Miami’s Condo Market Is Changing Again: Is the Window for Buyers Starting to Close?

October 8, 2026

Miami condo inventory has fallen for seven consecutive months, but buyers still have 12.1 months of supply. What happens if that supply keeps shrinking?
Miami skyline across the bay at sunset, beyond a palm-lined waterfront concert.

Events

Things to Do in Miami in October 2026: Events, Festivals & Experiences

Lucas Boccheciampe  |  October 1, 2026

Discover Miami’s Best Events, Concerts, Festivals, Food Experiences, and Halloween Celebrations This October
Waterfront homes and high-rise towers line a broad waterway at sunset.
Miami Houses vs. Condos: Why Buyers Are Facing Two Completely Different Markets

Lucas Boccheciampe  |  September 25, 2026

Miami Dade had 4.9 months of single family home inventory in August 2026, compared with 12.1 months for existing condos. Why does buying a house and buying a condo in … Read more
Waterfront restaurant terrace with palm trees and a high-rise skyline at dusk.

Events

Things to Do in Miami in September 2026: Events, Concerts, Food & Festivals

Lucas Boccheciampe  |  September 3, 2026

Your Complete Guide to Miami’s Best Concerts, Food Experiences, Sports, Art, Festivals and Cultural Events This September
Aerial waterfront neighborhood with luxury homes, a bay, and high-rise towers along the shore.

key biscayne

Hurricane-Resistant, Energy-Efficient Homes Are Redefining What Miami Buyers Want

Lucas Boccheciampe  |  August 20, 2026

Impact windows, insulated roofing, and smart-home systems have moved from luxury add-ons to non-negotiables, and the shift is reshaping how Miami's most discerning buy… Read more
Coconut Grove waterfront at sunset, with its stone sign, marina, and high-rises.

key biscayne

Four Seasons Private Residences Miami: Vertical Construction Begins in Coconut Grove

August 13, 2026

Florida's first standalone Four Seasons residential tower is rising above Biscayne Bay — here's what's confirmed, what's financed, and what it means for buyers.

Let's Talk

You’ve got questions and we can’t wait to answer them.